Construction Growth Hasn’t Disappeared. It Has Moved
The U.S. construction industry is entering a period of increasingly uneven growth. While overall construction spending is declining, several important market segments continue to expand, creating a widening divide between contractors positioned for growth and those facing a more challenging environment.
According to FMI’s latest 2026 North American Engineering and Construction Outlook, total U.S. construction spending is projected to reach $2.167 trillion this year, a 3.4% decline from 2025. That represents a significant downward revision from the firm’s previous forecast of a 1.3% decline.
The numbers tell an important story, but perhaps not the most important one.
The construction market is not simply shrinking. It is shifting.
Of the 19 construction segments tracked by FMI, only four are expected to grow in 2026. Five are relatively stable, while 10 are declining. Manufacturing construction, one of the industry’s strongest growth engines in recent years, has weakened significantly. Residential construction is also under pressure.
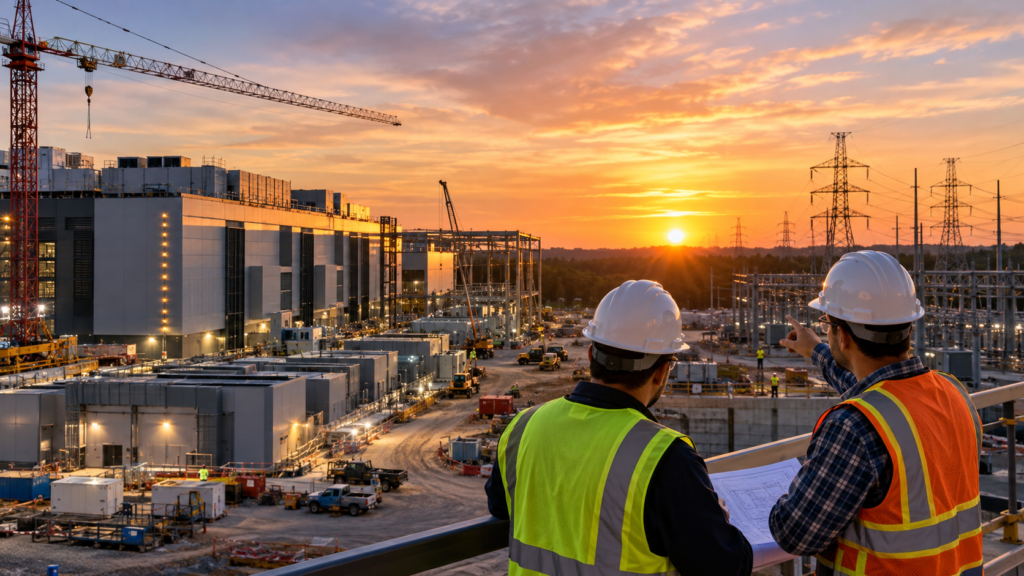
Meanwhile, data centers and power infrastructure continue to attract substantial investment.
For contractors, developers, suppliers and other construction industry stakeholders across the Carolinas, understanding where growth remains—and why—is becoming increasingly important.
A $2.17 Trillion Industry Moving in Different Directions
The construction industry’s current challenges reflect a combination of economic pressures, elevated borrowing costs, changing investment priorities and uncertainty surrounding public policy.
Residential construction has been particularly vulnerable.
FMI projects residential construction spending will decline 5.9% in 2026 to approximately $881 billion. Single-family construction is expected to fall 5.8%, while multifamily construction is projected to decline a more modest 1.4%.
Higher financing costs, affordability challenges and cautious consumer sentiment continue to weigh on housing investment.
Manufacturing construction has also lost momentum after several years of extraordinary investment associated with semiconductor production, electric vehicles, batteries and domestic industrial expansion.
The slowdown does not necessarily signal the end of America’s manufacturing investment cycle. Rather, it reflects a transition from the initial wave of major project announcements and construction starts toward a more selective investment environment.
For contractors that expanded capacity to serve these markets, the implications are significant.
The next phase of growth may require a different mix of customers, project types and capabilities.
Data Centers: The Industry’s Most Visible Growth Engine
Perhaps no construction market better illustrates the changing economy than data centers.
FMI forecasts office construction spending will increase 13.7% in 2026, but that headline masks two dramatically different trends.
Traditional office construction is projected to decline approximately 11%, while data center investment continues to accelerate.
According to the Census Bureau’s newly established data center construction category, spending reached an annualized pace of approximately $75 billion in July.
This growth is being driven by the extraordinary infrastructure requirements associated with artificial intelligence, cloud computing and the continued expansion of digital services.
But the opportunity extends well beyond the data center building itself.
These facilities require substantial investments in electrical distribution, substations, backup power, cooling systems, controls, automation and telecommunications infrastructure.
They also create demand for the manufacturing facilities that produce the equipment necessary to support this expanding digital infrastructure.
In many respects, data center construction is becoming an economic ecosystem rather than simply another commercial building category.
For contractors in the Carolinas, this creates opportunities across multiple disciplines, particularly electrical, mechanical, civil, industrial and specialty construction.
It also introduces new challenges.
Data center owners and developers increasingly expect contractors to demonstrate capabilities in accelerated project delivery, prefabrication, supply chain management, workforce planning and schedule certainty.
Winning in this market requires more than construction capacity. It requires the ability to manage complexity at scale.
Power Infrastructure: A Long-Term Construction Opportunity
While data centers are generating significant attention, power infrastructure may represent an even more consequential long-term construction opportunity.
FMI forecasts power construction spending will increase 4.9% in 2026, followed by stronger growth of 8.1% in 2027.
By 2030, annual power construction spending is projected to reach approximately $273 billion.
Several structural forces are driving this investment.
Electric utilities must accommodate rising electricity demand, replace aging infrastructure, improve grid reliability and connect new generation capacity.
The rapid expansion of data centers adds another layer of urgency.
Large industrial facilities, advanced manufacturing operations and the broader electrification of the economy are also contributing to growing demand for electrical infrastructure.
However, the sector faces significant constraints.
Long lead times for transformers, turbines and other critical equipment are delaying projects. Some major electrical equipment now requires procurement commitments years before installation.
These challenges are changing how projects are planned and delivered.
Owners and contractors must coordinate engineering, procurement and construction decisions much earlier in the project lifecycle.
For electrical contractors, industrial construction firms, equipment suppliers and engineering companies, the opportunity extends from major generation and transmission projects to substations, distribution upgrades, controls, automation and ongoing maintenance.
Importantly, these investments are not entirely dependent on a single economic cycle.
They reflect structural changes in how electricity is generated, distributed and consumed.
What This Means for Construction in the Carolinas
North Carolina and South Carolina are particularly well positioned to participate in several of these long-term investment trends.
The region benefits from population growth, a substantial manufacturing base, expanding logistics networks, established utilities and a growing concentration of technology-related investment.
However, these advantages do not guarantee that every construction market—or every contractor—will experience growth.
Several opportunities deserve particular attention.
1. Electrical Infrastructure and Power Delivery
The Carolinas’ growing population, industrial activity and technology investments are increasing the importance of reliable electrical infrastructure.
Opportunities extend beyond large power generation facilities to include substations, transmission and distribution improvements, electrical upgrades and maintenance.
Contractors with strong electrical capabilities, utility relationships and experience working in operating facilities may find opportunities even as other construction categories weaken.
2. Data Centers and Supporting Infrastructure
North Carolina has an established data center presence, while additional opportunities are emerging across the broader Southeast.
The construction opportunity includes not only large-scale facilities but also supporting power, cooling, telecommunications and equipment infrastructure.
For contractors, the ability to participate in this market may depend on specialized technical expertise, relationships with major owners and construction managers, and access to skilled labor.
3. Industrial Modernization and Automation
Although manufacturing construction spending is declining nationally, manufacturers continue to face pressure to improve productivity, reduce operating costs and modernize existing facilities.
This creates an important distinction between new manufacturing construction and investment within existing plants.
Facility upgrades, equipment installation, robotics, industrial automation, electrical modernization and process improvements may create opportunities even when new greenfield manufacturing projects slow.
For contractors serving industrial customers, maintenance and modernization could become increasingly important sources of recurring revenue.
4. Healthcare, Education and Institutional Investment
Healthcare, higher education and other institutional facilities remain important construction markets across the Carolinas.
While these sectors are not immune to financing pressures and budget constraints, demand for facility modernization, renovations, infrastructure improvements and specialized spaces can create opportunities independent of large new construction programs.
Contractors with established institutional relationships and capabilities in occupied-facility construction may be better positioned to capture these opportunities.
5. Renovation, Retrofit and Service
One of the most important strategic implications of a slowing construction market is the potential shift toward work within existing facilities.
Owners may delay major new construction projects while continuing to invest in assets they already operate.
That can create opportunities in electrical and mechanical upgrades, energy efficiency, building automation, maintenance, equipment replacement and facility modernization.
For contractors heavily dependent on new construction, expanding service and retrofit capabilities may provide a more balanced business model.
The Growing Importance of Geographic and Market Selection
National construction forecasts provide valuable direction, but they can also conceal substantial differences between local markets.
The Carolinas illustrate why geographic analysis matters.
Charlotte, Raleigh-Durham, Greenville-Spartanburg, Charleston and the coastal markets each have different economic drivers, customer concentrations and construction demand patterns.
A contractor operating in one market may experience strong demand from utilities, technology companies or institutional owners, while another faces declining activity in residential or traditional commercial construction.
The challenge for construction executives is to move beyond broad industry forecasts and understand the specific investment drivers within their geographic markets.
That requires examining announced capital projects, utility investment plans, industrial expansions, public infrastructure programs, institutional capital budgets and customer relationships.
It also requires distinguishing between projects that have been announced and those that are funded, permitted and likely to proceed.
In a more selective construction market, the quality of the opportunity pipeline matters as much as its size.
Five Strategic Questions Construction Leaders Should Be Asking
The changing construction outlook raises important questions for executives developing their 2027 business plans.
1. Are we positioned in the markets attracting capital?
Historical market strength does not necessarily indicate future growth. Contractors should evaluate whether their current sector exposure aligns with emerging investment priorities.
2. Are we overly dependent on new construction?
A business model concentrated in large new construction projects may be more vulnerable to financing conditions and investment delays. Service, maintenance, retrofit and modernization work can provide additional sources of revenue.
3. Do we have the capabilities customers will need next?
Growth markets increasingly require specialized technical expertise, sophisticated project delivery, supply chain coordination and advanced construction methods.
4. Are we building relationships early enough?
In sectors such as data centers and power infrastructure, procurement decisions and project team selection may occur long before construction begins. Early engagement with owners, engineers and major construction managers is becoming more important.
5. Are we planning for multiple economic scenarios?
With construction spending weakening and uncertainty surrounding financing, public funding and material costs, contractors should develop plans that account for different levels of market demand.
The objective is not to predict the future perfectly. It is to build an organization capable of responding as conditions change.
Beyond 2026: Preparing for the Next Construction Cycle
FMI’s latest forecast highlights several risks that could influence construction activity in 2027.
These include continued financing pressures, rising project costs, equipment availability and uncertainty surrounding federal infrastructure funding.
At the same time, the longer-term demand for digital infrastructure, electricity, industrial modernization and essential facilities suggests that significant construction opportunities will remain.
The challenge is that these opportunities will not be distributed evenly across sectors, geographies or contractors.
For construction companies, this creates a strategic imperative.
Business development strategies, workforce investments, technical capabilities and customer relationships must evolve with the markets.
Contractors that recognize changing demand early will have more time to develop expertise, establish partnerships and position themselves for the next wave of investment.
Those that rely exclusively on the markets and business models that drove their previous growth may find the transition more difficult.
The Bottom Line: Construction Growth Hasn’t Disappeared. It Has Moved.
A 3.4% decline in national construction spending is a meaningful signal that the industry faces a more challenging operating environment.
But the headline number does not tell the entire story.
The rapid expansion of artificial intelligence infrastructure, growing electricity demand, industrial modernization and the continuing need to maintain and upgrade existing facilities are reshaping the construction opportunity landscape.
For contractors across North Carolina and South Carolina, the central question is no longer simply whether construction spending will grow.
It is where investment is moving, which customers are making it, and what capabilities will be required to capture it.
The companies that answer those questions effectively will be better positioned to navigate the current slowdown—and capitalize on the next cycle of construction growth.
Source: FMI, 2026 North American Engineering and Construction Industry Overview, October 2026 forecast figures supplied for this article. National projections are not necessarily representative of individual Carolinas markets.